Holiday expenses go beyond gifts. Travel, food, decorations and seasonal activities can add up quickly, so include them in your spending plan.
You don’t have to spend equally on everyone or participate in every tradition. Setting expectations, comparing costs and choosing lower-cost alternatives can help keep spending manageable.
If holiday expenses or existing credit card debt are putting pressure on your budget, GreenPath’s free financial counseling can help you review your options.
The holidays can bring a lot of extra expenses at once. Between gifts, travel, family gatherings, decorations and everyday bills, even a well-planned budget can start to feel stretched.
And the pressure to make the season special can make it harder to stick to a spending limit. You might find yourself adding one more gift to your shopping cart, agreeing to an extra gathering or putting expenses on a credit card because there’s not enough money available right now.
You’re not alone in navigating those decisions. The National Retail Federation forecasts that U.S. retail sales during November and December 2026 will reach $1.013 trillion, a 4.2% increase over 2025.
But a memorable holiday season doesn’t have to mean spending more than you can afford. A little planning can help you make room for the traditions and people that matter without leaving you with a pile of bills in January.
How Do You Create a Holiday Budget?
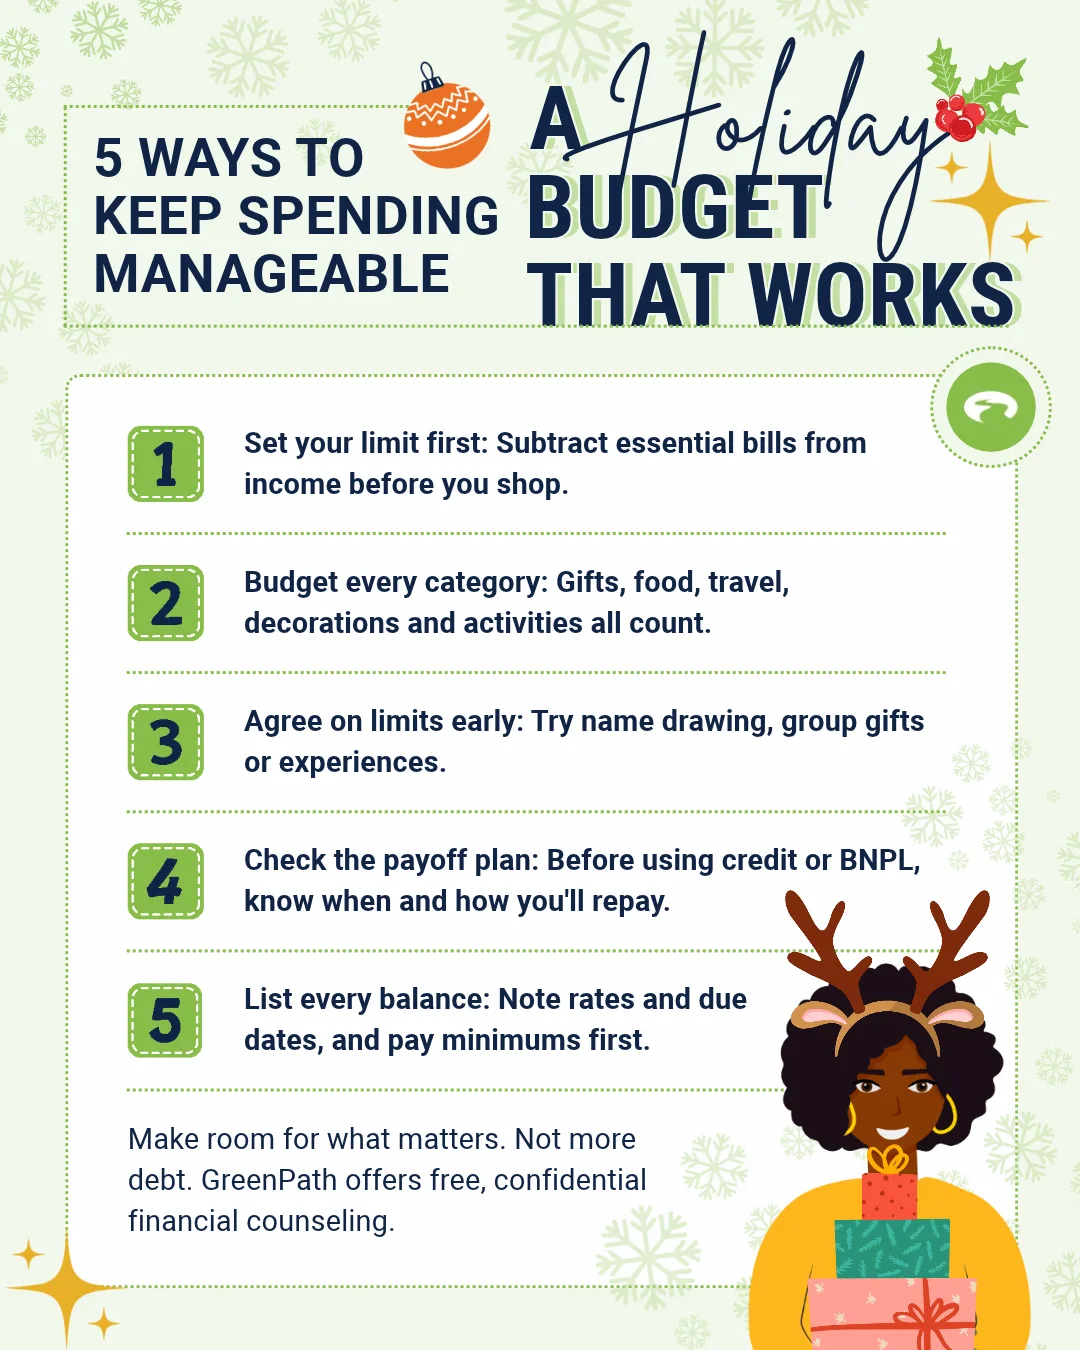
Start by figuring out how much you can realistically spend.
Before making a shopping list or browsing holiday deals, look at your regular monthly expenses, upcoming bills and current financial obligations. Consider what money will actually be available for holiday spending after essentials and required debt payments are covered.
Then build a holiday budget around the expenses you expect to have.
Include more than gifts. Your holiday spending may involve:
- Gifts for family, friends, coworkers and teachers
- Travel, gas, parking or lodging
- Groceries, holiday meals and entertaining
- Decorations, clothing and seasonal activities
- Charitable donations and holiday giving
- Shipping, gift wrapping and greeting cards
Give each category a spending limit based on what you can afford. If the total is higher than the money available, look for places to scale back before the season gets underway.
You can also use a budgeting worksheetbudgeting worksheet to get a clearer picture of your income, expenses and available money.
The goal isn’t to create a perfect budget. It’s to have a realistic spending plan that helps you make decisions before you’re standing at the checkout.
7 Ways to Save Money During the Holidays
Once you have a spending limit, look for practical ways to make your holiday budget go further.
1. Set Expectations About Gift Giving
Gift giving can be one of the biggest sources of holiday spending, especially when you’re buying for several people.
Consider talking with family and friends about setting spending limits, drawing names for a gift exchange or focusing on gifts for children rather than adults.
You can also suggest a group gift instead of buying something individually for everyone.
These conversations may feel uncomfortable at first, but setting expectations can help everyone avoid spending more than they intended.
2. Look for Meaningful, Lower-Cost Gifts
A thoughtful gift doesn’t have to come with a high price tag.
Consider what the recipient enjoys and look for ways to make the gift personal without stretching your budget.
A few ideas:
- Put together a movie-night basket with favorite snacks.
- Frame a family photo or create a small photo album.
- Make homemade treats or assemble a baking kit.
- Offer babysitting, help with a project or another service.
- Plan a shared activity or experience that doesn’t require an expensive outing.
You can also agree with family members to exchange experiences, handwritten notes or homemade gifts instead of purchasing something for everyone.
3. Plan Holiday Meals and Gatherings Together
Food and entertaining costs can add up, particularly if you’re hosting multiple gatherings.
If you’re planning a holiday mealplanning a holiday meal, consider making it a potluck. Ask guests to bring a favorite dish, dessert or beverage so the cost and preparation don’t fall entirely on one household.
Before shopping, check what you already have in your pantry and plan meals around ingredients you can use more than once.
You might also simplify the menu. A smaller gathering or fewer dishes doesn’t have to mean a less meaningful celebration.
4. Compare Prices Before Making a Purchase
Holiday sales can create a sense of urgency, especially when retailers advertise limited-time deals.
But a discount doesn’t automatically make something affordable—or mean it’s the best price available.
Before buying, compare prices across retailers and account for shipping, taxes and other fees. Check return policies, too, particularly when purchasing gifts.
It’s also worth asking whether the purchase was already part of your budget. Buying something you didn’t plan to purchase simply because it’s on sale can still put pressure on your finances.
5. Plan Travel and Seasonal Activities in Advance
Holiday travel and entertainment can create expenses beyond the obvious ticket or admission price.
If you’re traveling, account for transportation, lodging, meals, parking, and other costs. Compare options early when possible, and consider whether adjusting your travel dates or staying with family could reduce expenses.
For local activities, look for community events, free holiday displays, neighborhood celebrations, and other lower-cost ways to spend time together.
You don’t have to participate in every activity to enjoy the season.
6. Be Careful with Credit Cards and Buy Now, Pay Later
Credit cards and Buy Now, Pay Later (BNPL) services can make holiday purchases feel more manageable because you don’t have to pay the full amount immediately.
But spreading out payments doesn’t make an expense disappear.
A 2026 NerdWallet survey found that 19% of holiday spenders expect to have credit card bills they won’t be able to pay in full and on time. The survey also found that 15% expect to have Buy Now, Pay Later bills they can’t pay in full and on time.
If you’re considering using credit, think about how you’ll repay the purchase and whether the payment fits into your existing budget.
For credit cards, carrying a balance can mean paying interest long after the holidays are over. With BNPL, multiple payment schedules can make it harder to keep track of what you owe and when payments are due.
Before choosing either option, ask yourself:
- Can I afford this purchase without borrowing?
- When will the payment be due?
- Will I be able to make the payment without falling behind on other bills?
- Am I already carrying balances or paying off other installment purchases?
If you can’t comfortably answer those questions, consider a lower-cost alternative or waiting until you have the money available.
7. Give Yourself Permission to Say No
Not every invitation, gift exchange or seasonal activity needs to fit into your schedule or budget.
If an additional expense doesn’t work financially, it’s okay to decline or suggest another way to participate.
You might skip an expensive group outing, limit the number of gifts you exchange or suggest a casual gathering at home instead of going out.
It can help to decide in advance what you’re comfortable spending so you’re not making financial decisions under pressure.
The holidays don’t have to look a certain way to be meaningful.
What If You Can’t Afford Holiday Expenses This Year?
Sometimes, even careful planning doesn’t leave much room for additional spending.
If your regular bills, debt payments and everyday expenses already use most of your income, adding holiday purchases may create more financial pressure than they’re worth.
Start by prioritizing essential expensesprioritizing essential expenses, including housing, utilities, food, transportation, and required debt payments.
Then look at what you can realistically afford to spend on the holidays, even if that amount is smaller than you would like.
You may need to adjust expectations, simplify traditions, or focus on activities that don’t require much money.
It’s also worth being honest with family and friends about your budget. You don’t have to explain every detail of your finances, but letting people know you’re keeping spending modest can help avoid misunderstandings.
If you need to use credit to cover basic expenses, take that as a reason to review your overall budget rather than adding more holiday spending.
What Should You Do If You Already Have Holiday Debt?
If you’ve already made holiday purchases on credit cards or other borrowing products, don’t wait until the new year to understand what you owe.
Start by listing each balance, interest rate, minimum payment, and due date. Include Buy Now, Pay Later installments and any other payments that may be coming up.
Continue making at least the required minimum payments on your accounts and avoid adding new charges when possible.
If you have extra money available, consider directing it toward the balance with the highest interest rate while keeping your other accounts current.
You may also want to review your budget for opportunities to free up money for repayment.
Remember that paying off holiday debt may take time. The important thing is understanding what you owe and having a realistic plan for making progress.
Keep Exploring
Check out these related GreenPath resources for more guidance:
- Should You Build an Emergency Fund or Pay Off Debt First?:Should You Build an Emergency Fund or Pay Off Debt First?: Learn how to balance emergency savings with paying down high-interest debt.
- 7 Ways to Get Out of Credit Card Debt:7 Ways to Get Out of Credit Card Debt: Explore practical strategies for paying down credit card balances.
- Holiday Shopping Trap (Recorded Webinar):Holiday Shopping Trap (Recorded Webinar): Learn the tactics retailers use to drive impulse spending and how to shop more intentionally.
- When Giving Feels Heavy: Financial Self-Care for the Holidays:When Giving Feels Heavy: Financial Self-Care for the Holidays: Consider ways to manage financial pressure and set boundaries around holiday spending.
How GreenPath Can Help You Manage Holiday Debt
Holiday spending can put additional pressure on a budget, particularly if you’re already managing credit card debt or struggling to keep up with monthly expenses.
GreenPath offers free, confidential financial counseling with NFCC-certified counselors who can review your income, expenses and debts, answer questions and help you understand your options.
If high-interest credit card debt has become difficult to manage, a counselor can also explain whether a Debt Management Program (DMP)Debt Management Program (DMP) may be appropriate for your situation.
A DMP is not a loan or debt settlement. For eligible unsecured debts, it provides a structured repayment approach through one monthly payment. Depending on the creditor, concessions may include reduced interest rates or waived fees.
You don’t have to wait until holiday debt becomes overwhelming to ask for help. Understanding your options can help you decide what makes sense for your finances now and in the months ahead.
Ready to Talk to a Counselor?
If holiday expenses or existing debt are making it difficult to keep up with your budget, GreenPath’s financial counselors can help you review your situation, understand your options and identify practical next steps—without judgment.